One of the first steps of home buying in Orange County is to determine your estimated borrowing power. When you’re making offers, it’s important to know how seriously a lender took the time to check your financial profile. Working with Nathan Carpenter can help you better understand your financing position before moving forward.
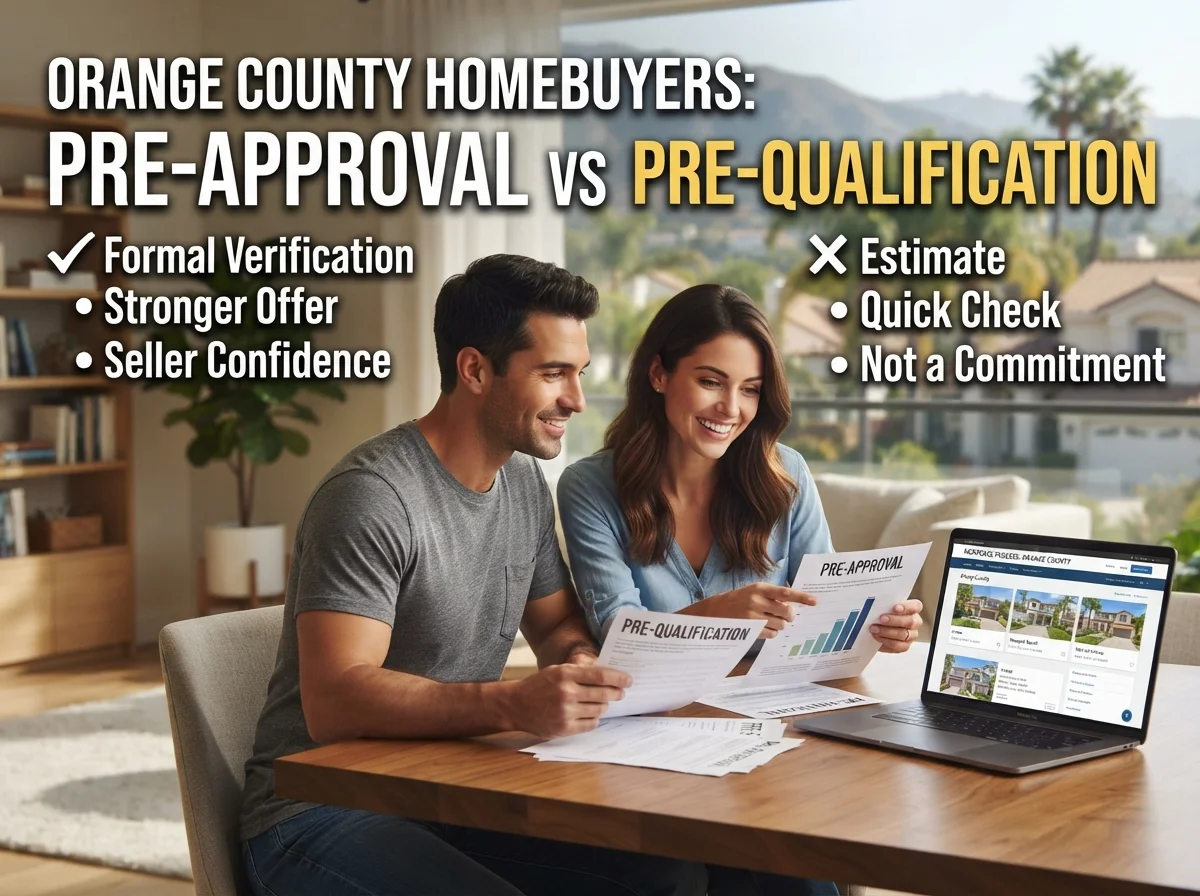
This is where the difference between mortgage pre-approval vs. pre-qualification comes in. While these terms can often be used interchangeably, there may be varying degrees of documentation, credit review, and lender verification. Knowing those differences can help you budget more realistically for the home buying process.
Pre-Qualification and Pre-Approval at a Glance
The most significant difference is typically the volume of details the lender sees. But there is no common industry definition, and all lenders don’t necessarily use these terms in the same way. Consumer Financial Protection Bureau points out that lenders can use the terms “prequalification” and “preapproval” interchangeably.
| Factor | Mortgage Pre-Qualification | Mortgage Pre-Approval |
| Financial information | Often based largely on information you provide | Usually involves more detailed review |
| Credit review | A credit check might not be required | Typically involves a credit check |
| Documentation | Often lighter | Usually more documentation |
| Borrowing estimate | Preliminary | More thoroughly evaluated |
| Home search | Useful for early planning | More useful when preparing to make offers |
| Final loan guarantee | No | No |
The key is not only what is written on the letter, but also what happens after it’s opened. Inquire with the lender what information was checked and what is still pending.
What Pre-Qualification Can Tell You Early On
Mortgage pre-qualification can be helpful if you’re not sure that homeownership is possible. You can give them details of your income, debts, assets, and how much you want to borrow, and the lender may use those to make an estimate of what you may be able to borrow.
This can be useful to help get a baseline for the home search budget before starting through the most in-depth process of getting a mortgage. The CFPB notes that some lenders use unverified information provided by the borrower to prequalify them, whereas other lenders may engage in a more comprehensive lending process.
| Quick Note: Always ask the lender what was actually verified before relying on the letter. |
What Makes Pre-Approval Different?
The pre-approval of a home mortgage tends to be more comprehensive. This can include a credit check, income verification, bank statements, employment details, debt details, and any other financial documents, depending on the lender.
This leaves you with a preapproval letter that indicates that the lender is tentatively willing to lend a certain amount, with assumptions and conditions. This is not a final mortgage approval. The terminology still varies between mortgage lenders, so two lenders may use the same word for processes that are not identical. The better question is: How much of my financial profile have you reviewed?
Which One Makes More Sense for Orange County Buyers?
Your stage in the homebuying process matters.
A pre-qualification might be helpful if you’re considering buying and wondering if you’re financially prepared. For those searching for properties and planning to make an offer to purchase, a more comprehensive pre-approval will usually be more valuable.
This is important in Orange County because it’s a big investment. Realtor.com reported a countywide median sold price of $1,225,000 in September 2026, while Redfin reported a median sale price of $1,220,914 for August 2026.
Those figures do not determine what an individual buyer should spend. They simply show why understanding financing before choosing a price range is particularly important in this market.
How Credit and Documentation Fit Into the Process
One of the areas that buyers must watch is credit review. Your credit score and history may be checked by a lender when deciding whether to provide a loan and the terms offered. The CFPB states that lenders typically conduct a credit check when considering a borrower for mortgage pre-approval.
You may also need financial documents such as:
- Recent pay stubs
- W-2 forms
- Bank statements
- Tax returns when requested
- Information about existing debts
- Proof of available funds
- Employment information
Don’t think that a pre-qualification implies that you’ve already submitted all the documentation. A lender may ask for more information at a later time.
Orange County Loan Limits Can Affect the Conversation
Local home prices also make loan limits worth understanding. The conforming loan limit for a single-unit home in Orange County is $1,249,125. The limit will be raised for properties with multiple units.
This is not to say all customers should have a loan that is nearly as large. The amount you can qualify for depends on your income, credit score, debt, down payment, loan program, and monthly payment.
| Helpful Note: A loan limit is not the same as your personal borrowing limit. |
For instance, if someone wants to purchase a home that is near the median price of the county, they may still have to calculate how much money they will need for the down payment and closing costs, as well as how much they can afford each month.
What Sellers Actually Need to See
The key advantage of a pre-approval letter is that it provides a seller with proof that a lender has looked at your financing profile and is willing to loan you the money. The CFPB explains that sellers frequently require preapproval before accepting an offer, although the letter does not guarantee that the mortgage will ultimately close.
The letter can state the loan amount and other pertinent information, but the buyer should discuss conditions that have yet to be addressed with the lender. A real estate agent will also be able to better explain the kind of financing paperwork that is usually required when making an offer on the local market.
How Long Does a Pre-Approval Last?
Generally, a pre-approval letter will come with an expiration date. The CFPB reports that these letters are often issued for 30-60 days, but the length of time is determined by the lender. If you’re preparing to enter the market, learning how to get pre-approved before buying can help you understand what to expect before you start making offers.
If your letter expires before you have located a lender, a lender may request new income, asset, employment, or credit data. Your financial situation should also remain stable during the home search. New debt, a job change, or major financial transactions could affect your mortgage assessment.
A Better Way to Compare Your Options
Instead of just asking yourself whether you need pre-qualification or pre-approval, think about where you are in your home buying journey and what you need right now.
If you are still planning:
- Review your income and recurring debts.
- Estimate your available down payment.
- Explore potential monthly payments.
- Ask about suitable mortgage loan programs and which options may fit your financial situation.
- Consider obtaining a preliminary qualification.
If you are ready to shop seriously:
- Gather your financial documents.
- Compare multiple mortgage lenders.
- Ask what the lender will verify.
- Request a detailed pre-approval.
- Confirm how long the letter remains valid.
The CFPB suggests you should always compare offers and try to get pre-approved by at least three lenders before you pick a mortgage. For Orange County buyers, Nathan Carpenter can be part of the early mortgage conversation when you need to discuss your mortgage options and prepare for the next stage of buying a home.
Frequently Asked Questions
Is pre-qualification easier than pre-approval?
Most of the time, pre-qualification is easier and lighter on paperwork; it usually leans more on what you share with the lender. However, lenders use these terms their own way, so don’t just go by the name. Make sure you ask what financial details the lender actually checked, like your income, assets, debts, and credit.
Does pre-qualification affect your credit score?
It really depends on the lender’s process. Some lenders just use your info without doing a hard credit check. Others will pull your credit report. The CFPB says you should always ask if the lender plans to check your credit before you move forward with pre-qualification or pre-approval.
Do I need pre-qualification or pre-approval before making an offer?
A more thoroughly reviewed pre-approval is generally more useful when you are ready to make an offer. Sellers frequently request a pre-approval letter because it provides evidence that financing has been reviewed. However, the letter is still not a guarantee of final mortgage approval.
Can I choose a different lender after getting pre-approved?
Yes. A pre-approval does not commit you to using that lender for the final mortgage. The CFPB actually encourages you to compare multiple lenders and review Loan Estimates to figure out which offer is the best fit for you.
How early should I get pre-approved?
A lot of buyers go for pre-approval right when they’re serious about shopping for a home, since most letters are only good for 30 to 60 days. If you initiate the process ahead of time, you may identify credit or documentation problems before getting to the offer stage.
Final Thoughts: Choose the Financing Step That Matches Your Buying Stage
The difference between pre-qualification and pre-approval becomes especially important once you are ready to purchase. A preliminary qualification may help establish an estimated budget, while a more thoroughly reviewed pre-approval provides stronger financing information when you begin preparing offers.
With Orange County’s median sold price at $1,225,000 in September 2026 and the county’s 2026 one-unit conforming loan limit at $1,249,125, understanding your financing position before choosing a purchase price is especially valuable.
Before you start house hunting, review your financials, work out your monthly payment, compare different lenders, and make sure your target price makes sense for your actual budget. Nathan Carpenter can help you take a more informed approach to the mortgage process before moving forward with a home purchase