The VA home loan may be particularly beneficial to prospective home buyers looking to purchase a home in Capistrano Beach, as home values here are much higher than in other markets in California. The median sale price of a home in Capistrano Beach rose 20.1% year over year over the past three months to $1,999,035. Homes were sold at a median price of $1100 per square foot, and on a median day, were held up for sale for 50 days.
If you are a veteran or active service member in Orange County who is looking into this market, a VA Loan Officer in Capistrano Beach, CA, can help you understand the eligibility, entitlement, financing costs, and how to secure a VA-backed home loan. Nathan Carpenter can help eligible borrowers review their available financing options and understand the VA loan process.
Why VA Financing Can Be Valuable in Capistrano Beach
The biggest advantage is that qualified borrowers can potentially purchase a home with zero down payment and no monthly private mortgage insurance (PMI). Purchase loans are also available and can be competitive, and VA will permit borrowers to use their benefit more than once if they qualify.
It’s important in Capistrano Beach because the person who saves 20% on a $1,999,035 home would be saving nearly $400,000 in cash. For individuals who meet certain eligibility requirements, a VA loan can eliminate the requirement for a conventional down payment, even though income, credit,
| VA Feature | What It Means for Buyers |
| Down payment | Potentially 0% for eligible borrowers |
| Monthly PMI | Not required |
| Funding fee | Usually applies unless exempt |
| Primary residence | Required for a standard purchase loan |
| Credit score | VA itself does not set a minimum, but lenders may |
| Property value | A loan generally cannot exceed the lower of the purchase price or the appraised value |
| Loan limits | Full-entitlement borrowers generally have no VA-set loan limit |
VA states that they don’t require a minimum credit score, but that individual lenders may set their own.
Are You Eligible for a VA Home Loan?
Your eligibility starts with your military service and Certificate of Eligibility (COE). Qualifying service may consist of active duty, some National Guard/Reserve service, and other situations.
For example, current VA guidance states that veterans are eligible if they served from August 2, 1990, to the present, the entire duration of at least 90 days of being called or ordered to active duty, or an exception that satisfies the requirements. The required service period may also be impacted by a service-connected disability discharge.
Eligible surviving spouses may qualify in certain circumstances as well. The COE can be issued directly by the VA, or a lender may be able to request the COE for you electronically.
What the Lender Reviews
A COE is a statement of eligibility, but it does not guarantee that the lender will loan the money. The lender will still review:
- Credit history and credit report
- Income and employment history
- Existing debts
- Debt-to-income ratio
- Assets and available funds
- Monthly mortgage payment
- Property value and condition
- Occupancy plans
For a typical VA home purchase loan, the property must be your primary residence.
A $2 Million Capistrano Beach Home: What Changes?
Capistrano Beach’s local pricing makes entitlement and appraisal particularly important.
If you have full VA entitlement, there is no VA capped loan amount. The borrower still needs to qualify with the lender, and the property must appraise sufficiently. If a borrower doesn’t have full entitlement, one of the factors that may limit the amount they can finance without a down payment is the county loan limits.
Orange County’s 2026 one-unit conforming loan limit is $1,249,125. This figure can matter when calculating the remaining entitlement for borrowers who have already used some of their VA benefit. It is not a rule that a VA veteran with 100% eligibility can only take a $1,249,125 VA loan.
For instance, a veteran who purchases a $2 million home on Capistrano Beach with full entitlement may have the option to finance the home without a down payment if the buyer’s credit is good and the appraisal backs the home’s purchase price. The remaining entitlement may be different for a veteran with remaining entitlement.
The VA Funding Fee: Know the 2026 Numbers
While monthly mortgage insurance isn’t required with a VA loan, most borrowers will end up paying a one-time VA funding fee unless they are exempt.
The current funding fee for a first-time VA purchase (with less than 5% down) is 2.15%. It goes down to 1.5% if your down payment exceeds 5%, and 1.25% if it’s 10% or more. The rate is typically 3.3% with less than 5% down when used for reuse.
As an example, the funding fee for the $1,000,000 first-use VA loan with no down payment would be about $21,500 for a borrower who is not exempt. This fee can typically be rolled into the loan rather than be paid at closing.
Veterans who are receiving VA disability compensation for a service-connected disability, or a disability with certain conditions, may not have to pay the funding fee.
What About VA Closing Costs?
Zero down doesn’t mean no closing costs. There are still lender charges, appraisal fees, title and escrow fees, prepaid taxes and insurance, recording fees, and other fees associated with the transaction that a buyer can expect to have to pay. VA rules also restrict certain charges and allow seller concessions in qualifying transactions.
Carefully review the Loan Estimate and Closing Disclosure before signing. These documents will reveal the estimated and actual mortgage expenses, making it simpler to track adjustments prior to signing.
VA Appraisals Are Not the Same as Home Inspections
Many VA-backed purchase transactions will need a VA appraisal, but it’s not the same as a professional home inspection.
The VA appraisal becomes a part of the appraisal, and it is used to determine if the property is eligible for the loan and whether the value is adequate. VA updated its Minimum Property Requirements and appraisal procedures in June 2026, including changes intended to reduce outdated requirements and appraisal delays.
Buyers should also research the condition, drainage, exposure to moisture, and other property-specific concerns about the property that are not covered by the VA appraisal for a coastal property at Capistrano Beach.
VA Purchase Loan vs. VA Refinance Options
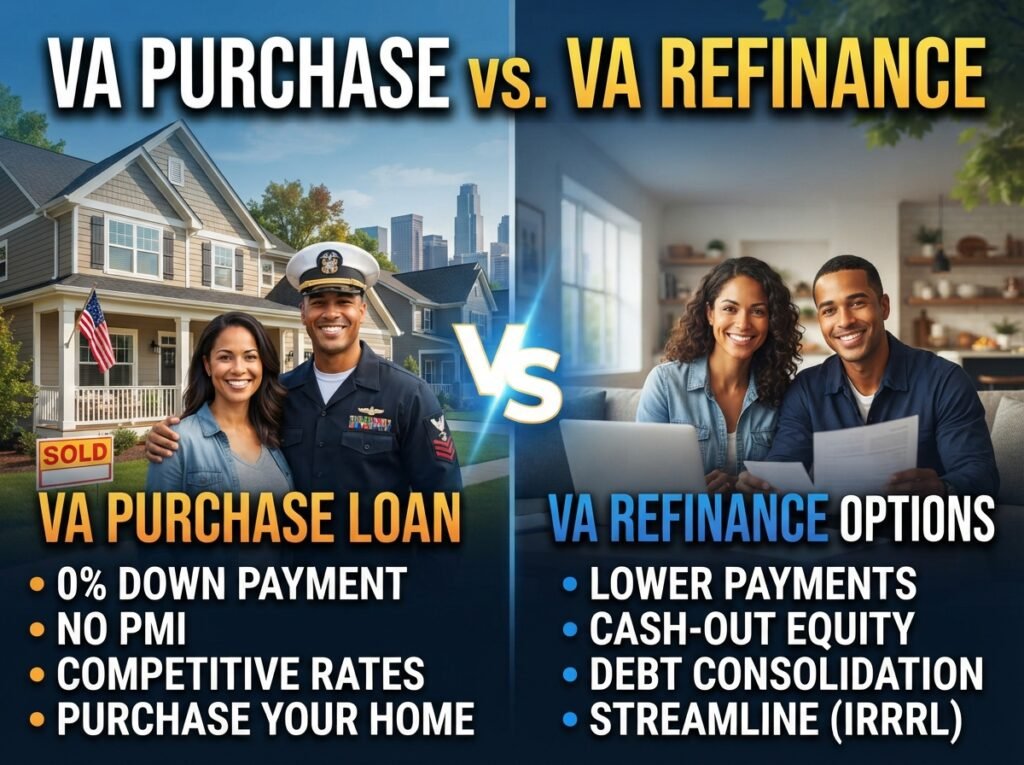
A VA home loan helps eligible borrowers purchase a qualifying home they plan to live in. But the VA program also provides refinancing options.
The Interest Rate Reduction Refinance Loan (IRRRL) can be used by eligible borrowers to refinance an existing VA loan, generally with the goal of reducing the interest rate or making payments more stable. A new COE is not required for an IRRRL.
A VA cash-out refinance is another option that can allow qualified homeowners to refinance and access home equity. However, refinancing creates new costs, so the potential benefit needs to be compared with the new loan’s interest rate, fees, and long-term expenses.
A Practical VA Homebuying Roadmap
If you are planning to buy in Capistrano Beach, the process can be easier when handled in this order:
1. Confirm eligibility: Obtain your COE and review your remaining VA entitlement.
2. Review your finances: Check credit, income, debts, assets, and your comfortable monthly payment.
3. Get VA pre-approved: A lender can establish an estimated borrowing range before you make an offer.
4. Shop for the property: Focus on homes that meet your budget and VA occupancy requirements.
5. Make an offer: Your real estate and lending professionals can help structure the financing terms.
6. Complete appraisal and underwriting: The lender verifies the borrower and property before final approval.
7. Review closing documents: Check your Loan Estimate, Closing Disclosure, funding fee, lender charges, and other costs.
8. Close: Once all conditions are satisfied, the purchase can be completed.
A VA financing professional can help you understand where your loan stands throughout these stages.
When Should You Work With a VA Loan Specialist?
A VA loan expert can be particularly helpful when the purchase involves a high-value property, previous VA loan usage, limited remaining entitlement, or questions about funding fees and closing costs. Buyers can also review this VA loan guide for Orange County when comparing their financing options.
Nathan Carpenter can help eligible borrowers review their VA financing options and understand how the program may fit a Capistrano Beach home purchase.
Do not compare loans based only on the advertised interest rate. Ask about the complete monthly payment, funding fee, lender fees, closing costs, appraisal requirements, and how much cash you will actually need to close.
Frequently Asked Questions
Can I buy a $2 million home in Capistrano Beach with a VA loan?
Potentially, yes. A borrower with full VA entitlement may be able to finance a higher-priced property without a down payment if the lender approves the loan and the appraisal supports the purchase price. Borrowers without full entitlement may face different entitlement calculations.
Does a VA loan require a minimum credit score?
The VA itself does not establish a minimum credit score for its home loan program. However, individual lenders can impose their own credit requirements. Your complete financial profile, including income, debts, employment, and credit history, will affect approval.
Do veterans have to pay the VA funding fee?
Not always. Certain veterans and service members are exempt, including borrowers receiving VA compensation for a qualifying service-connected disability. Other eligible exemptions may apply. Borrowers who are not exempt generally pay the applicable funding fee based on loan use and down payment.
Can I use my VA loan benefit again?
Yes. Eligible borrowers can use their VA benefit again after selling or refinancing a previous VA-financed property, subject to entitlement and lender requirements. If you have already used part of your entitlement, the remaining amount needs to be reviewed before determining the financing structure.
Final Thoughts: Using Your VA Benefits in Capistrano Beach
With a $1,999,035 median sale price in Capistrano Beach, VA, financing can provide meaningful flexibility for eligible veterans who want to purchase in this Orange County coastal community. The combination of no required monthly PMI, potential zero-down financing, and flexible entitlement rules can make the program worth considering.
Nathan Carpenter can help you evaluate the numbers before you make an offer, including your entitlement, funding fee, expected closing costs, and monthly payment. If you are ready to discuss your situation, contact Nathan Carpenter to review your VA financing options. A careful pre-approval and property-specific review can help you use your VA benefits with fewer surprises.