Yes, you can buy a new house before selling your current home, but approval depends on your income, existing mortgage, cash, and lender rules. Some buyers carry two homes briefly; others use home equity or a sale contingency.
Your choice depends on the likely sale timeline and how much financial pressure you can handle. Compare both homes’ costs and plan for a delayed sale before making an offer.
Can You Buy Another House While You Still Have a Mortgage?
An existing mortgage does not automatically prevent another purchase. A lender checks whether your income and assets can support the new loan while you keep paying the current one. Credit history, down payment, reserves, and monthly debts all affect the decision.
Lenders also consider taxes, homeowners insurance, association dues, and other debts. If your home is under contract, the lender may review the sale documents and cleared financing conditions before deciding how to count its payment.
How Your Existing Mortgage Affects Qualification
Your debt-to-income ratio (DTI) compares monthly debt payments with gross income. For example, $4,000 in monthly debts against $10,000 gross income equals a 40% DTI. A second housing payment can raise this ratio and reduce your borrowing room.
Fannie Mae generally requires both housing payments to be counted if the current home has not sold before the new purchase closes. The existing payment may be excluded with an executed sale contract and confirmation that financing contingencies are cleared. The lender reviews the full file.
Gather your mortgage statement, estimated home value, income documents, credit details, and other debts. Estimate sale proceeds after the mortgage payoff and selling costs to understand how much cash may remain for your next down payment.
Financing Options for Buying Before Selling
Home equity may fund the next purchase, but each method adds costs or repayment duties. Compare terms with a lender before relying on those funds.
| Option | How it works | Main concern |
| Bridge loan | Short-term financing covers the gap between purchases. | Higher costs and a repayment deadline. |
| HELOC | Lets you draw against equity in your current home. | Often variable-rate and adds debt. |
| Home equity loan | Provides a lump sum secured by your property. | Adds a payment and possible upfront fees. |
| Savings | Uses cash you already have for the down payment. | May leave too little for emergencies. |
A HELOC or home equity loan uses your current home as collateral, putting it at risk if you cannot repay. HELOC rates are often variable. Check fees, draw limits, and repayment terms before borrowing.
A bridge loan may suit buyers with strong equity, but fees and repayment dates vary. Estimate net sale proceeds before assuming the sale will repay it.
Should You Make a Sale-Contingent Offer?
A home sale contingency makes your purchase dependent on selling your current home by an agreed date. It reduces the risk of two mortgages, but sellers may prefer offers without this condition.
A realistic sale deadline, listing plan, and mortgage pre-approval can support your offer. Ask your agent and real estate attorney to review the contingency dates and protections.
What Santa Ana’s Housing Market Means for Your Timing
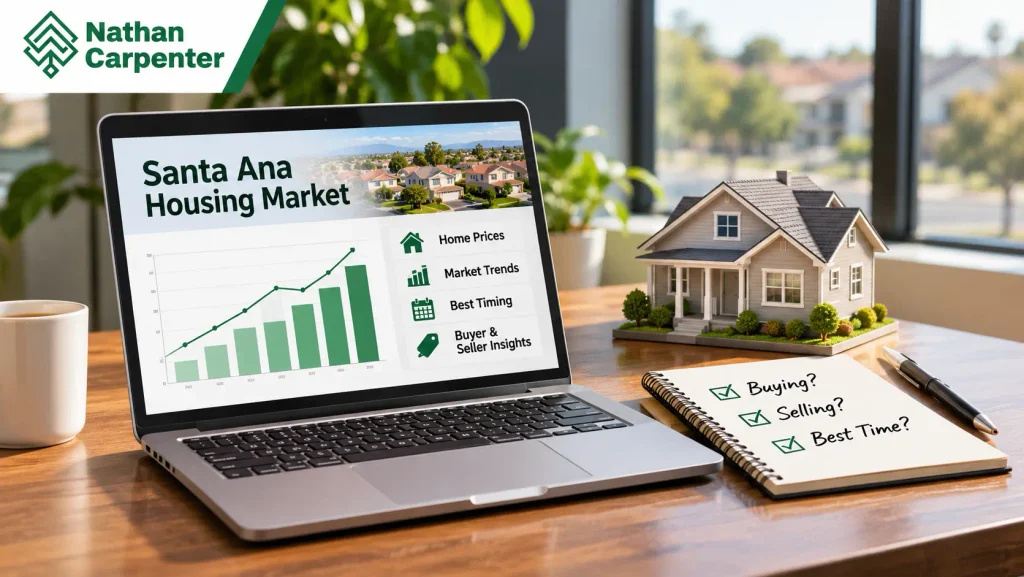
Santa Ana timing deserves attention. Redfin reported a median sale price of $849,595 in September 2026, up 3.7% year over year, and a 44-day median selling period. Realtor.com reported 54 median days on market for September, using a different data set.
These figures are context, not a promise for your property. Price, condition, and home type affect timing. Freddie Mac’s latest survey before November 5 showed a 7.24% average 30-year fixed rate on October 29, 2026; your offer may differ.
Get a property-specific price review and estimate proceeds after payoff, selling costs, and repairs. Nathan Carpenter can help you consider the sale timeline and purchase plan. Keep a backup if the sale takes longer.
How to Reduce the Risk of Carrying Two Homes
Budget for a delayed sale. Include both mortgage payments, taxes, insurance, utilities, maintenance, moving costs, and any down payment loan. Keep emergency savings separate from closing funds.
Before committing, work through these steps:
- Get pre-approved using both housing payments.
- Ask how a pending sale or rental plan affects qualification.
- Confirm the cash remaining after down payment and closing costs.
- Set a realistic sale price and timeline with your agent.
- Decide what you will do if the home does not sell on time.
If you cannot cover both homes comfortably, consider selling first, negotiating a rent-back, or arranging temporary housing. Loan approval is not the same as affordability.
Frequently Asked Questions
Can I buy a house before selling if I already have a mortgage?
Yes, if you qualify for the new loan while meeting your current mortgage obligations. The lender reviews income, credit, DTI, assets, and cash reserves. Some buyers can carry both payments, while others need a sale contingency or another financing plan.
Do I have to sell my house before buying another one?
No. There is no general rule that requires you to sell first. However, the lender may count both housing payments when reviewing your application. Selling first can reduce financial pressure, while buying first may give you more time to find a suitable home.
Can I use a HELOC for the down payment on another house?
You may use HELOC funds if the lender permits the source and you qualify for the added debt. The HELOC payment can affect your DTI, and the credit line is secured by your current home. Review its rate, fees, and repayment terms before drawing funds.
What happens if my current house does not sell after I buy another one?
You remain responsible for the mortgage, taxes, insurance, and other costs associated with both properties. If you cannot manage those payments, you may need to reduce the asking price, consider renting the old home, or explore other options before your savings run low.
How much equity do I need to buy another house before selling?
There is no single equity amount that works for every buyer. Your available equity depends on your home’s value and outstanding mortgage balance. A lender also considers loan-to-value limits, borrowing costs, credit, income, and the down payment required for the new property.
Final Thoughts: Make Your Next Home Purchase Without Overstretching Your Budget
Buying before selling can work when your finances, loan approval, and sale timeline support the move. Compare the full cost of both properties, confirm how the lender treats your existing mortgage, and keep reserves for delays. For help planning a Santa Ana move, contact Nathan Carpenter before setting your purchase and sale dates.