Ready to begin your home search in Orange County, California? Before you start looking at houses or submit an application, one of the first things you need to do is obtain a mortgage pre-approval. It gives you a good idea of how much you can borrow, and it allows a seller to know that you have begun the loan process.
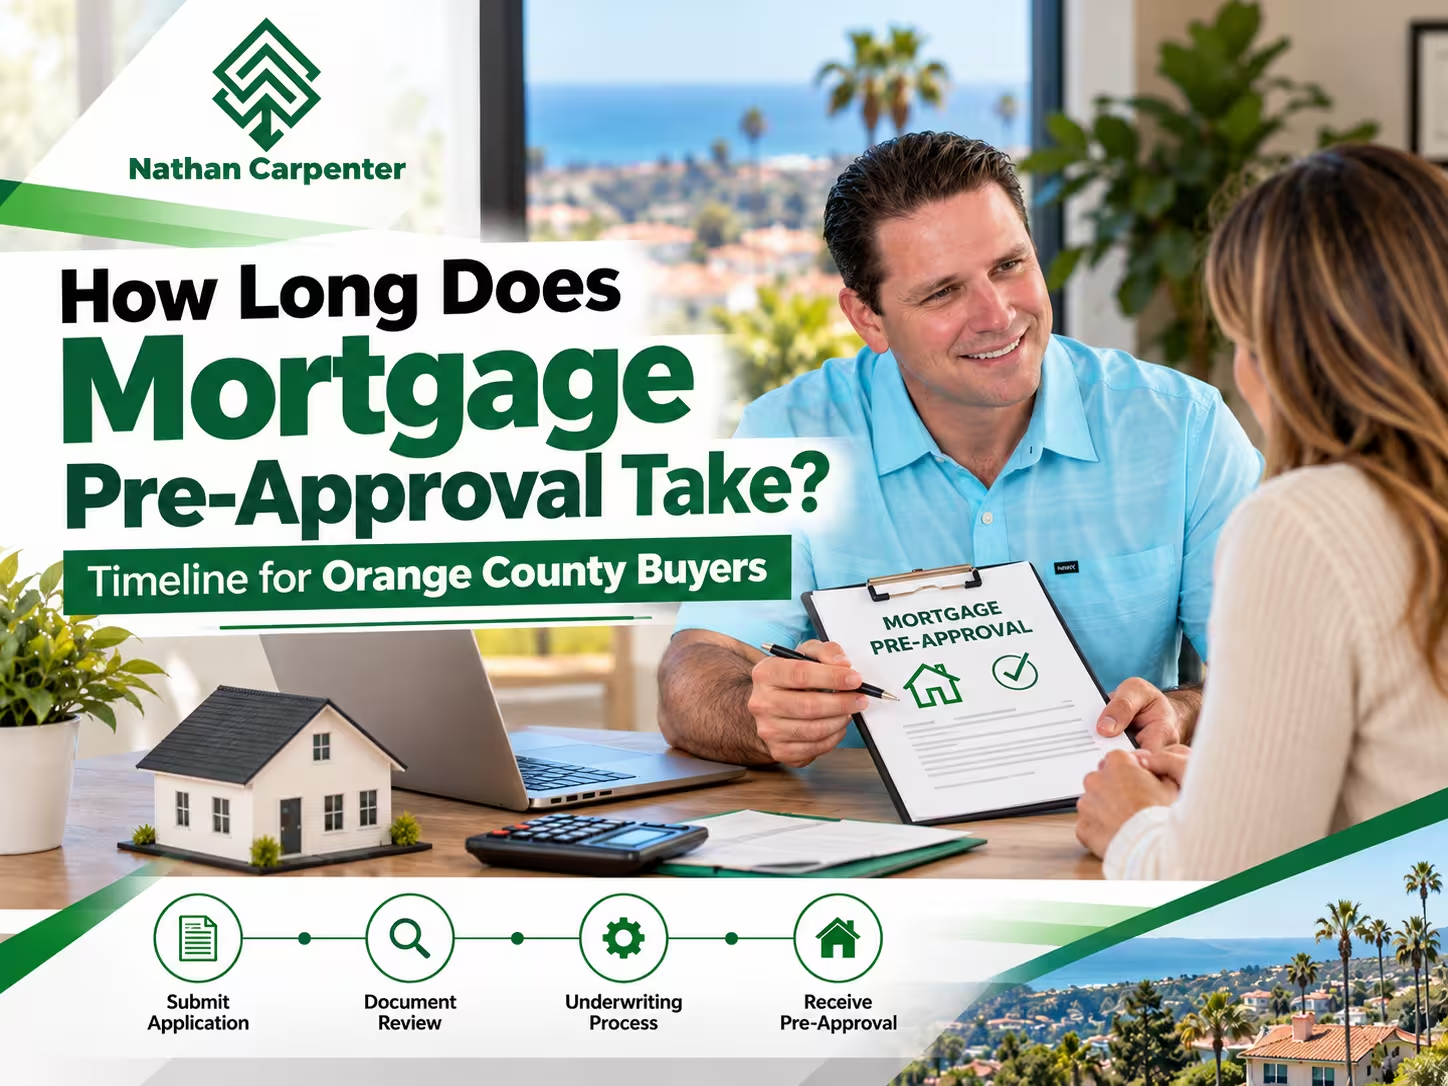
So, how long does mortgage pre-approval take? If your application is simple and your documents are in place, you can get a decision on your application within one to three business days. Other, more complicated applications can take several days or even longer, depending on the lender, income sources, credit history, and verification requirements.
What Is the Typical Mortgage Pre-Approval Timeline?
There is no universal processing time. Some lenders perform an automated check of loan applications and can provide a pre-approval letter in a few moments, while others require further paperwork or checks before they can give a pre-approval letter.
Here is a practical estimate of how the main stages may fit together:
| Stage | Estimated time |
| Complete the application | Same day to 1 day |
| Credit check and initial review | Same day to 1 business day |
| Income, employment, and asset verification | 1–3 business days or longer |
| Resolve questions or missing information | A few extra days, if needed |
| Receive the pre-approval letter | Often within 1–3 business days for straightforward applications |
These are planning estimates, not guaranteed lender deadlines. Some lenders may provide a letter on the same day, but the process can take longer if you are self-employed and have some irregular income or haven’t finished the necessary paperwork.
What Happens During Each Stage?
Application and credit check
It starts with you providing information about your income, debts, assets, employment, and how much you’d like to borrow. The lender typically will be looking at your credit to review your borrowing history and obligations.
Before applying, review your credit reports for errors and avoid taking on new debt unnecessarily. A credit check is a component of a financial profile; it doesn’t guarantee approval by itself.
Document review and financial verification
Then the loan officer will check your supporting documents. These can include recent pay stubs, W-2s, tax returns, bank statements, and any other debts. Your lender may verify your job and investigate the source of your funds for the home purchase.
Straightforward salaried income may be easier to document than variable commissions or self-employment income. If the lender finds a mismatch or needs clarification, the application may remain under review until you provide the missing information.
Pre-approval letter
Once the lender has reviewed the information required for its pre-approval process, it may issue a letter stating the approximate amount it is tentatively willing to lend. The letter can serve as a useful tool to help you and your real estate agent determine an appropriate price range.
However, pre-approval is not a final mortgage commitment. After making an offer, the loan process continues as the lender verifies your finances, reviews the property, and goes through underwriting.
Why Orange County Buyers Should Prepare Early
Before you even start looking for a house, it’s essential that you understand your financing options, particularly if you’re going to be comparing local prices. According to the California Association of REALTORS®, the median sold price for an existing single-family home in Orange County was $1,467,500 in March 2026. This is a dated market figure, not a current quote or a prediction of what an individual property will cost.
Buyers should be aware, at this level of pricing, how their down payment, monthly payment, credit history, and cash will impact their budget. While a pre-approval can provide a baseline, the maximum loan amount does not necessarily mean the amount that a household should borrow.
Start the process before you plan to make offers. This will provide you with enough time to work on the problem of missing documents or money/loan concerns without becoming cramped for time to satisfy a seller’s deadline.
What Can Delay Mortgage Pre-Approval?
Even a well-prepared buyer can face additional review. Delays most often result from the following issues:
- Missing documents: Unavailable bank statements, outdated pay stubs, or incomplete tax returns may require follow-up.
- Self-employment or variable income: The lender may need more evidence to understand income consistency.
- Unexplained deposits: Large or unusual deposits may require documentation showing where the funds came from.
- Credit or debt questions: Errors, new accounts, or obligations that were not included initially can trigger further review.
- Slow responses: Each day spent waiting for requested information can extend the mortgage pre-approval timeline.
To reduce avoidable delays, gather your paperwork in advance and respond promptly to your loan officer.. Keep documents legible, provide complete statements when requested, and ask what else the lender needs before considering the file ready for review.
It is also useful to understand common pre-approval mistakes to avoid before submitting an application. Applying without checking your financial details or making major financial changes during the process can create complications that take extra time to resolve.
How Can You Get Pre-Approved Faster?
You don’t have a lot of control over what the mortgage lender does along the way, but you can make it more efficient on your part.
Use this preparation checklist:
- Gather recent pay stubs and the tax documents relevant to your income.
- Collect checking, savings, and investment account statements.
- Prepare details of monthly debts, including car loans and credit cards.
- Have your employment history and residential history available.
- Explain unusual deposits or gifts intended for your down payment.
- Submit complete information and check messages from your loan officer daily.
You can also contact Nathan Carpenter to ask about document review, secure digital verification, and when to expect an update.. It will also help you to have an understanding of your lender’s communication and what documents they need.
If you are buying your first home, reviewing first-time buyer loan options in California can help you understand how different financing programs may affect down payment requirements and eligibility. Do not make assumptions about what programs might be available to the buyer, because they vary based on circumstances.
Does Pre-Approval Mean Your Mortgage Is Approved?
No. Pre-approval is a preliminary judgment that is made on the information presented at the time. A final mortgage approval typically means a more thorough look at the borrower’s financial circumstances, property, and any stipulations imposed on the mortgage loan.
A pre-approval letter does not last forever. The Consumer Financial Protection Bureau points out that most expire between 30 and 60 days, but the exact timeline depends on your lender. If your search is prolonged, verify whether your lender requires updated financial information.
Don’t open new credit accounts, make big deposits without explanation, or change jobs unless you talk it over with your lender. Any major change in your finances can mess with your loan, even after you have a pre-approval letter.
Frequently Asked Questions
Can I get mortgage pre-approval in one day?
Yes, some lenders will give you a letter the same day if everything’s simple and you have your documents ready. Other lenders need more time to verify details.
Does mortgage pre-approval affect my credit score?
Most lenders will check your credit during pre-approval. How much it affects your score depends on the type of inquiry and your overall credit history. Ask your lender exactly how they plan to check your credit before you start.
When is the right time to submit an offer?
Start your search when you know your budget, but obtain a recent pre-approval letter prior to making an offer, particularly if the seller or market requires it. Make sure your letter matches the price range you want.
Final Thoughts: Plan Your Financing Before House Hunting
Getting pre-approved can take a day or a few days, depending on how fast your lender reviews your info. If you pull your documents together early, respond quickly, and ask clear questions, you can avoid a lot of delays.
For Orange County buyers, it isn’t just about having a letter fast. It’s about knowing your budget, understanding the terms, and being clear on your next steps before you make a big financial move. Nathan Carpenter can help buyers seeking guidance as they prepare for the home-buying process.