Self-employment does not prevent you from buying a home. Freelancers, contractors, gig workers, and business owners can qualify for conventional, FHA, VA, and other mortgages. The challenge is proving reliable income.
Your revenue may change, and business expenses or tax deductions can complicate income verification. Underwriters look beyond gross sales and deposits to assess qualifying income and business stability. Organized records make the process easier.
What Factors Do Mortgage Lenders Review for Self-Employed Applicants?
Lenders assess whether your business can produce enough income to cover personal obligations. They review earnings, business finances, credit, debts, and savings. For many conventional loans, 25% or greater business ownership is considered self-employment.
Underwriters commonly examine:
- Income stability: Are earnings consistent, rising, or declining?
- Business history: How long has the business operated? Do you have relevant experience?
- Cash flow: Can the business cover expenses and provide income to you?
- Credit and debt: Do you manage existing payments responsibly?
- Savings: Can you cover the down payment, closing costs, and required reserves?
Income need not be identical each month, but its documented pattern must support qualification.
How Is Self-Employment Income Calculated?
Lenders do not qualify you on gross revenue or deposits alone. They use tax returns and other records to calculate stable income after eligible expenses and adjustments.
| Business structure | Common documents |
| Sole proprietor | Form 1040 with Schedule C |
| Partnership | Form 1065 and Schedule K-1 |
| S corporation | Form 1120-S, K-1, and personal return |
| Independent contractor | 1099 forms and applicable tax schedules |
A sole proprietor with $120,000 in revenue and $45,000 in expenses is not automatically credited with $120,000 in personal income. The lender reviews net income and may add back permitted non-cash expenses, such as depreciation.
For partnerships and S corporations, underwriters may review distributions and business liquidity. Fannie Mae Form 1084 analyzes cash flow.
How Many Years of Self-Employment Do You Need?
Two years is a common guideline, but not an absolute rule. Fannie Mae may allow less than two years if the latest signed personal and business returns show a full 12 months of current business income and the borrower documents prior work in the same or a similar field at a comparable income level.
A designer moving from agency work to freelance work may qualify if earnings support continuity, but approval is not guaranteed.
FHA loan requirements typically call for a two-year work history. In some cases, borrowers with one to two years may qualify if they previously worked in the same or a related occupation for at least two years. Confirm current rules with the lender.
What Documents Should You Prepare?
Documents verify personal income and business stability. Requirements vary.
Prepare to provide:
- Personal tax returns: Usually the latest two years, with relevant schedules.
- Business tax returns: Often required for partnerships and corporations.
- IRS transcripts: Lenders may request transcripts through Form 4506-C.
- Current profit and loss report: Summarizes your business earnings, operating costs, and net profit for the year so far.
- Business bank statements: Help document deposits and cash flow.
- 1099s, K-1s, or Schedule C: Support income from contract work and business structures.
- Business records: A license or formation documents may verify ownership and operating history.
Separate business and personal transactions so deposits and expenses are easy to explain.
What If Your Income Fluctuates or You Claim Large Deductions?
Fluctuating income is not an automatic disqualifier. Stable or rising earnings may support qualification; a significant decline can reduce qualifying income or require evidence of recovery.
Tax deductions can also affect approval. Business expenses reduce taxable net income, which may lower the amount used to qualify. Some permitted adjustments can be added back, but not every deduction is reversed. Ask a mortgage professional to review filed returns before applying.
Which Mortgage Options Are Available?
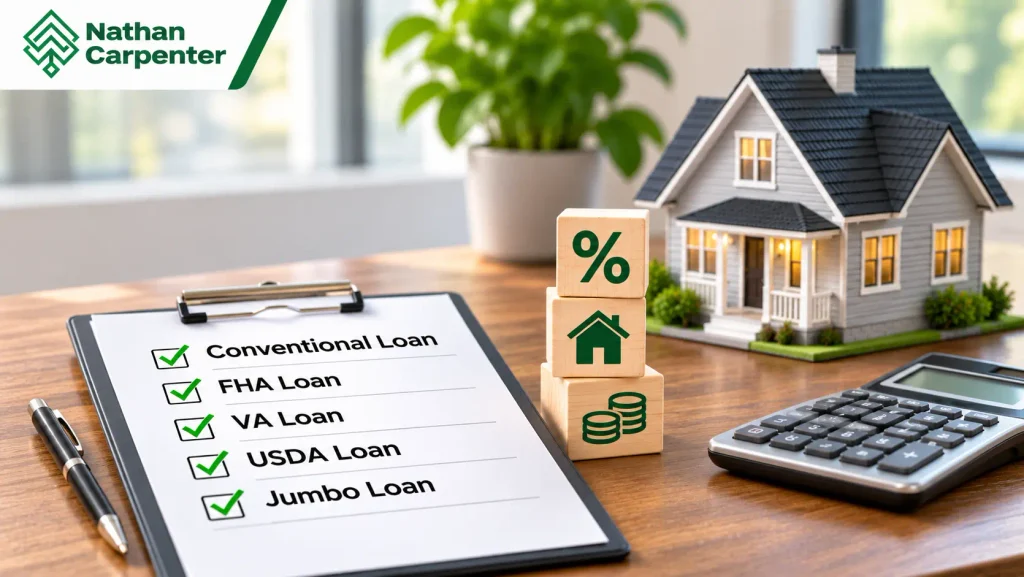
Self-employed applicants can use many of the same loan programs as salaried borrowers. Eligibility depends on income, credit, down payment, property, and program rules.
- Conventional loans: Use Fannie Mae or Freddie Mac methods to review tax returns and business cash flow.
- FHA loans: May offer flexible credit and down-payment requirements, while still requiring stable, documented income.
- VA loans: Eligible veterans and service members can use VA financing, with self-employment income verified.
- Bank statement loans: Some non-QM lenders assess eligible business deposits instead of relying only on tax returns. These programs may have different rates, down payments, and reserve requirements.
Nathan Carpenter can review your documents before you shop. According to Realtor.com, homes in Santa Ana had a median listing price of $849,444 in October 2026. Orange County’s 2026 conforming limit for a one-unit home is $1,249,125. Neither figure determines approval; income, debts, down payment, taxes, and insurance shape affordability.
How Can You Improve Your Approval Chances?
Get pre-approved using reviewed documents before making offers.
- Review credit reports and correct errors.
- Hold off on opening new credit lines or taking on large purchase payments.
- Pay down revolving balances where practical.
- Organize recent personal and business bank statements.
- Set aside enough money for closing expenses and ongoing business operations.
- Document unusual deposits and separate business spending.
- Review your debt-to-income ratio (DTI) with your loan officer.
No single DTI percentage guarantees approval; lenders consider the full financial profile and loan program.
Frequently Asked Questions
Do lenders use gross or net income?
They generally calculate qualifying income from tax returns and eligible adjustments, not gross revenue alone. Depending on your business structure, the review may include net profit, depreciation, distributions, and cash flow.
Is Mortgage Approval Possible With Only One Year of Self-Employment?
Possibly. Some conventional guidelines allow it with 12 months of current business income and documented prior experience in a similar field. In some cases, FHA may accept a self-employment history of just one or two years.
Do business expenses reduce how much I can borrow?
They can. Expenses usually reduce reported net income, which may lower the amount used to qualify. Some adjustments are allowed, but not every expense is added back.
Can freelancers and gig workers qualify?
Yes. Freelancers, consultants, and gig workers may qualify with documented earnings and a reliable work history. Lenders may review 1099s, tax returns, bank statements, and current income records.
Can a bank statement loan help if tax returns show low income?
Some non-QM programs use eligible deposits to estimate income. They may suit business owners with substantial deductions, but can require larger down payments, stronger reserves, or higher rates.
Final Thoughts: Get Your Self-Employment Income Mortgage-Ready
Self-employed borrowers can qualify when records show stable income. Review tax returns, cash flow, credit, and debts before house hunting. Nathan Carpenter can explain mortgage options and documentation for buyers in Santa Ana and Orange County.